Take this year’s membership income, add the proposed subscription increase and carry the total into next year’s budget.
It is a straightforward calculation. But it assumes the members, categories and payment patterns behind that income will stay broadly the same.
As golf clubs across the UK and Ireland prepare their 2027 membership budgets, those assumptions deserve closer attention. A credible forecast needs to explain who will renew, who might leave, where new members will come from and when the money will arrive.
The Met Office provisionally recorded summer 2026 as the UK’s hottest on record. Met Éireann also reported a record warm summer for Ireland, with below-average rainfall overall. Local experiences varied, however, so national weather headlines cannot explain every club’s performance.
For your budget, the question is how those conditions affected your club. Did more playable days support visitor income? Did heat or course conditions change when members played? Were new joiners attracted by a particular offer?
Meanwhile, the Bank of England’s September assessment highlighted the impact of Middle East conflict on energy prices and inflation risks. For golf clubs, that creates potential pressure on operating costs and on the household budgets from which subscriptions are paid.
With shorter days and winter ahead, a strong summer should inform the forecast without becoming an assumption that next year will repeat it.
Before setting the 2027 baseline, establish the membership position you expect to reach at the end of December.
Start with current active, paying members by category. Add realistic expectations for the remaining months, including confirmed departures, outstanding renewals, likely joiners and agreed category changes.
This gives you your 2026 exit run-rate: the ongoing membership income represented by the members you expect to carry into 2027, at current fees.
Keep one-off joining fees, temporary promotions and exceptional receipts separate. Avoid simply multiplying a good summer month by twelve.
Then apply proposed 2027 prices separately, so the committee can see how much growth comes from fee increases and how much depends on membership changes.
Build the forecast category by category, separating:
Opening members and renewals are not two separate groups to add together. Renewals describe what happens to existing members when their current terms end.
Likewise, a flexible member upgrading to full membership is a category transfer, not both a resignation from the club and a new acquisition. Record the movement in both categories, but count the person once.
Use recent renewal history, member conversations, playing activity and enquiry conversion to support your assumptions. An ambitious recruitment target needs a credible plan behind it.
A single forecast can conceal how much depends on everything going to plan.
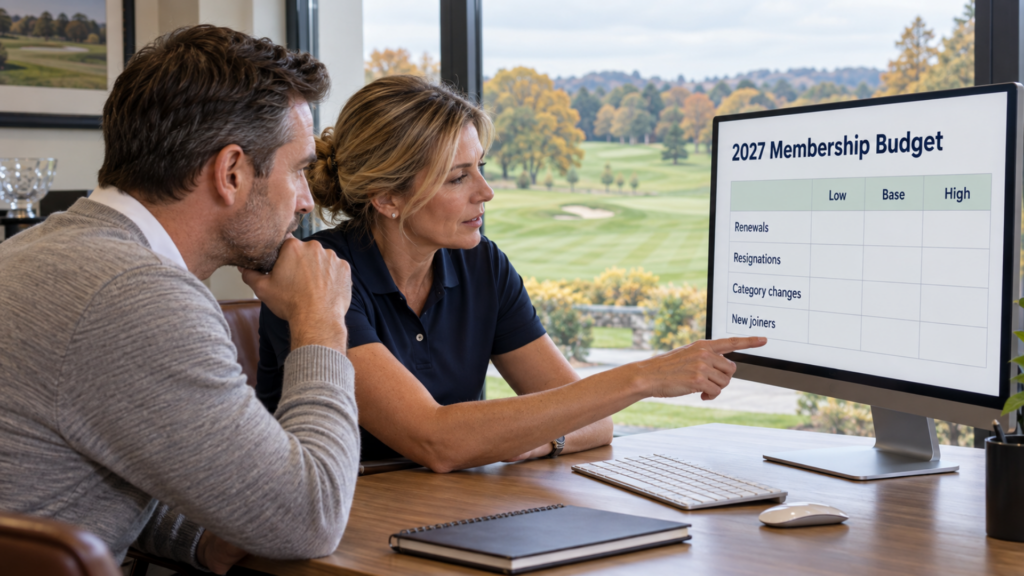
Build three versions using different assumptions about renewal, category movement and recruitment:
Change the underlying member numbers and joining dates, rather than simply adding or subtracting a percentage from the annual total.
This shows the committee which risks matter most and what action could improve the outcome.
An existing membership commitment and a hoped-for visitor booking provide different levels of certainty.
Separate membership income already contracted from expected renewals and future sales. Forecast visitor income separately, distinguishing confirmed bookings from enquiries and bookings still to be generated.
Flexible membership can help clubs convert some occasional golfers into an upfront membership commitment. However, future flexible membership sales still need forecasting; they are not secured income until golfers commit.
Use the club’s retained income after applicable fees and allocations when assessing its contribution. The golfer’s headline membership price is not automatically the amount available to the club.
An annual total can look healthy while individual months remain difficult.
Phase the forecast by renewal dates, expected joining months, instalment schedules and payment terms. Reflect winter’s reduced daylight and potential disruption when forecasting visitor bookings.
Keep monthly revenue and cash receipts distinct. An annual subscription paid upfront can support cash flow immediately, while the associated revenue may be recognised across the membership period.
This matters when winter maintenance, staffing and other bills fall before the main renewal receipts arrive.
The Membership Revenue Planning Workbook provides a focus for bringing these questions into your budget discussions. Use it alongside your membership records to document assumptions, compare scenarios and review monthly income expectations.
Where validated, anonymised PlayMoreGolf renewal, resignation and category-movement ranges are available, use them to sense-check your forecast. Comparisons should reflect similar clubs, categories and reporting periods; your own evidence should remain the starting point.
Before approving the budget, ask: can we explain the members, movements and payment dates behind this number?
If the answer is clear, your club will be better placed to spot a shortfall early and act while there is still time.
We use cookies to improve your experience. You can accept or reject non-essential cookies.